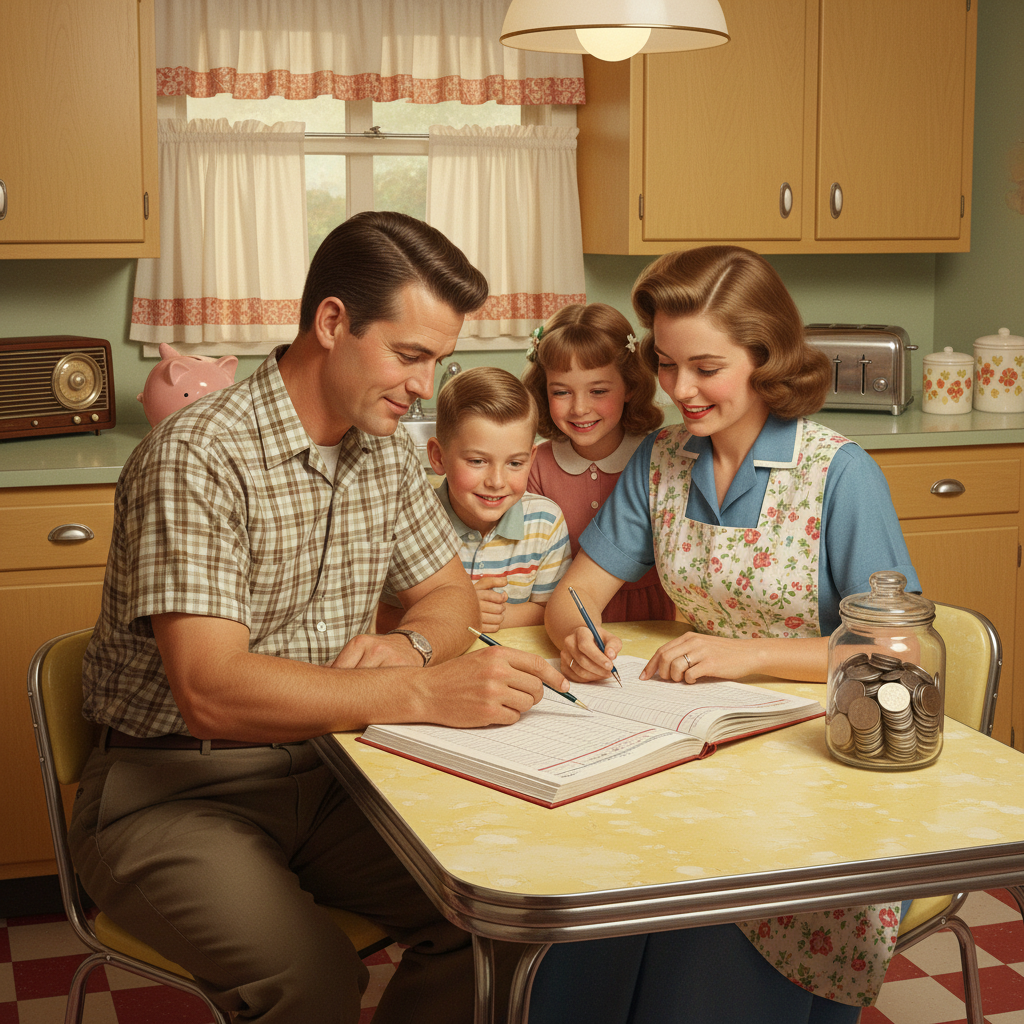
My father kept a small green ledger in the kitchen drawer.
Not a spreadsheet. Not a financial planning app. A ledger, a narrow clothbound notebook he bought at the drugstore for thirty-five cents, where he recorded every dollar that came into the Vasquez household and every dollar that left it. Groceries, the gas bill, the mortgage payment, the two dollars he slipped into the church envelope every Sunday. All of it, in his careful handwriting, every single week for thirty-one years.
I thought it was old-fashioned when I was young. I think it might be genius now.
The Mid-Century Money Philosophy Nobody Called a Philosophy
The households of the 1950s and early 1960s operated on a set of financial principles so embedded in daily life that nobody thought to name them. They were just how things were done.
You didn't buy what you couldn't pay for. You saved before you spent. You kept something back for hard times, which were always considered possible if not inevitable. You fixed things rather than replacing them. You considered whether you truly needed something before you bought it, and often concluded you didn't.
None of this was particularly glamorous. It wasn't meant to be. It was meant to keep the lights on and leave something behind.
Ward Cleaver, that impossibly patient father from Leave It to Beaver, embodied this ethos in every episode. Calm, measured, never rattled by money because he had made sure money would never rattle him. Was he a TV character? Of course. But he reflected something real: a generation of men who had lived through the Depression and World War II and came home determined that their families would never want for what they could reasonably provide.
And June? June Cleaver is usually remembered for her pearls and her vacuum cleaner. But look more closely. She was managing a household economy, tracking what food cost, making things last, turning leftovers into Tuesday's dinner, stretching a budget in ways that required genuine intelligence and planning. The domestic sphere wasn't decorative. It was financial infrastructure.
What They Got Right: Five Principles That Still Hold
**1. They paid themselves first — they just called it something else.**
Before direct deposit and automatic transfers, the classic move was the "envelope system." Cash divided at the beginning of the month into labeled envelopes: rent, groceries, utilities, savings. The savings envelope wasn't optional. It was the first one filled.
Modern financial planners call this "paying yourself first." Your grandparents called it Tuesday. The principle is the same: savings is not what's left over after spending. It's what comes out first.
**2. They were deeply skeptical of debt.**
The generation that survived the Depression had a visceral, almost physical discomfort with owing money. They would save for years to pay cash for a car. They made extra payments on the mortgage whenever they could. Credit cards, when they finally arrived, were treated with enormous wariness.
This wasn't ignorance. It was wisdom earned the hard way. Compound interest, they understood intuitively, works against you just as powerfully as it works for you.
**3. They thought in decades, not quarters.**
They didn't have 24-hour financial news channels telling them what the market did today. They bought U.S. Savings Bonds, put money in passbook savings accounts, and contributed to pension plans with the quiet confidence that patience was rewarded. They were right.
The data consistently shows that long-term, low-turnover investing outperforms active trading for most ordinary investors. Your grandfather's boring "set it and forget it" approach would make most modern day traders blush.
**4. They understood the difference between a want and a need.**
This sounds simple because it is, but it's a discipline that the consumer culture of the last sixty years has systematically dismantled. When a new appliance appeared in the Sears catalog, the question wasn't "do I want this?" It was "do we need this, and if we buy it, what do we not buy?" Every purchase was understood to have a cost beyond its price tag.
**5. They left something behind.**
The concept of a financial legacy, leaving something meaningful for the next generation, was baked into how they approached everything. Life insurance was not optional. The paid-off house was something to pass down. A small savings account for the grandchildren was a point of pride. They thought past themselves.
What We Can Borrow From Their Playbook
I'm not suggesting we return to the days of a single income, no retirement accounts, and a savings bond as the pinnacle of investment sophistication. The financial landscape is genuinely more complex now, and there are real tools available today that our parents could only have dreamed of.
But the principles underneath all of it? They haven't changed.
I started keeping a ledger a few years after David died. Not quite as meticulous as my father's, but in the same spirit. I write down what I spend, every week, in a notebook. It's humbling. It's clarifying. It connects me to something my father knew that I took thirty years to understand: that paying attention to money is not about anxiety or scarcity. It's about respect. For what you earned. For what you still have. For the people who might one day benefit from your carefulness.
Ward Cleaver would understand. And June, I suspect, would nod.
A Few Things Worth Doing — Whatever Your Age
If you're in your 60s or 70s and feel like the financial picture is complicated, it can be. But a few things remain timelessly useful:
Review your spending honestly. Not to judge yourself, but to know. Knowledge is not anxiety; ignorance is.
Make sure you have a will, an updated beneficiary designation on your accounts, and that someone you trust knows where everything is. This is perhaps the most loving financial act a person can perform for their family. The National Institute on Aging has a helpful guide on getting your affairs in order if you're not sure where to start.
Consider whether the next generation knows what you know. The financial habits your parents modeled for you were a form of education. Are you passing that on?
And perhaps most importantly: don't let perfect be the enemy of good. You don't need a perfect financial plan. You need a reasonable, consistent, patient one. The kind that Ward Cleaver probably had in that calm, book-lined study, and my father had in a thirty-five-cent ledger in the kitchen drawer.
Some wisdom, it turns out, doesn't expire.
---
**Financial Disclaimer:** This article is for informational and educational purposes only and does not constitute financial or investment advice. The experiences and strategies shared reflect the author's personal situation and should not be taken as a substitute for consultation with a licensed financial advisor or planner. Individual financial circumstances vary. Please consult a qualified financial professional before making any significant financial decisions.